How Much Is Motorcycle Insurance in a Big City vs Rural?
It's a question many riders ponder: "Will my motorcycle insurance cost more if I live in a bustling city compared to a quiet rural town?" It's a valid concern because, let's face it, every dollar counts, especially when you're budgeting for your riding lifestyle. The short answer is, yes, where you hang your helmet often significantly impacts your premium. This comprehensive guide will break down exactly why location matters so much for motorcycle insurance rates, exploring the factors that insurance companies weigh when pricing your policy based on your address.
The Urban vs. Rural Divide in Motorcycle Insurance Costs
Riding in a big city offers a certain kind of thrill – the lights, the sounds, the constant movement. But it also comes with a unique set of challenges and risks that insurance companies take into account. Conversely, the open roads of rural areas might feel safer, yet they have their own set of considerations. Understanding these differences is key to making sense of your premiums.
Higher Risk in Densely Populated Areas
When you're navigating the concrete jungle, you're constantly dealing with more traffic, more intersections, more distractions, and simply more opportunities for things to go wrong. Insurance companies see this increased exposure to potential accidents as a higher risk, and higher risk almost always translates to higher premiums.
Imagine riding through downtown Los Angeles during rush hour versus cruising on a two-lane highway in rural Montana. In the city, you're constantly braking, accelerating, swerving around potholes, dealing with aggressive drivers, and watching out for pedestrians and cyclists. Every mile ridden in a dense urban environment statistically presents more chances for a fender bender or a more serious collision. This isn't just a feeling; statistics often back this up. For instance, according to data analysis, urban areas typically report a higher incidence of traffic accidents, and motorcycles, being less visible, are often at a disadvantage in such scenarios.
Increased Theft and Vandalism Rates
Big cities, unfortunately, are also often hotspots for motorcycle theft and vandalism. A beautiful Harley-Davidson or a sleek sport bike parked on a city street can be an attractive target for thieves. Insurance companies track these statistics meticulously. If you live in an area known for high vehicle theft rates, your comprehensive coverage — which covers non-collision incidents like theft, fire, and vandalism — will likely be more expensive.
Think about it: A secured garage in a quiet rural subdivision versus street parking in a busy urban neighborhood like parts of Chicago or New York City. The likelihood of your motorcycle being tampered with or stolen is simply higher in the latter. Even if you have a top-tier alarm system or a heavy-duty chain, the sheer volume of potential perpetrators and the ease with which a stolen bike can be "disappeared" into an urban network makes it a bigger gamble for insurers. This is why when you're looking for What Does Full Coverage Motorcycle Insurance Mean?, the theft component is a significant factor in urban areas.
Factors Contributing to Higher Urban Premiums
Beyond just the general "higher risk" umbrella, several specific elements come into play that can inflate your motorcycle insurance costs if you reside in a major metropolitan area. These aren't always obvious, but insurers have teams of actuaries whose job it is to quantify these precise risk factors.
Traffic Density and Accident Frequency
The sheer volume of vehicles on the road in places like Atlanta, Houston, or Philadelphia dramatically increases the potential for accidents. More cars, trucks, buses, and other motorcycles mean more interactions, more blind spots, and more quick decisions that can lead to unfortunate outcomes.
When a motorcycle is involved in an accident, the injuries to the rider and damage to the bike are often more severe than in a car accident. This means higher potential payouts for medical claims (covered by bodily injury liability or MedPay) and repair or replacement costs (covered by collision coverage). The more frequently these incidents occur in a specific zip code, the higher the base rate will be for everyone insured in that area. It's an unfortunate reality of risk pooling – even if you're a meticulous, safe rider, you're still part of the statistical landscape of your local area. This is also why checking your Average Motorcycle Insurance Cost by State can reveal broad trends, but drilling down to zip code level is where the true cost variations emerge.
Higher Cost of Repairs and Medical Services
Everything costs more in big cities, right? That generally extends to motorcycle repairs and medical services. Auto body shops in prime urban locations often have higher overheads (rent, labor costs) which get passed on to the consumer – and, by extension, to insurance companies in the form of higher claim payouts.
Similarly, if you need medical attention after an accident, the cost of an ambulance ride, emergency room visits, specialist consultations, and physical therapy can be significantly higher in urban hospitals compared to their rural counterparts. Insurance companies factor these potential expenses into their premiums. When you file a claim, whether it's for property damage or personal injury, the payout is directly influenced by the local cost of services. So, a crash in Manhattan will likely incur higher repair and medical costs than an identical crash in upstate New York. This impacts all parts of your policy, including liability coverage and comprehensive plans.
Uninsured and Underinsured Motorists
While this isn't exclusively an urban problem, densely populated areas tend to have a higher prevalence of uninsured and underinsured motorists. This means if you get into an accident and the other driver is at fault but doesn't have adequate insurance (or any at all), your own Uninsured Underinsured Motorist Coverage UM UIM becomes vital.
Insurance companies charge more for this coverage in areas where the risk of encountering such drivers is higher. For example, in states like Florida, where there's a significant number of uninsured drivers, regardless of urban or rural, UM/UIM coverage is strongly recommended. The increased density in cities simply compounds this issue, making it more likely that you'll cross paths with someone who isn't properly covered, forcing your insurer to pick up the tab through your own policy, leading to higher premiums for everyone in that risk pool.
The Rural Advantage (and its own considerations)
Living in a rural area often brings with it the promise of lower insurance rates. Less traffic, fewer people, and generally lower crime rates contribute to this. However, it's not without its own unique set of factors that can influence your policy.
Lower Risk Profile and Fewer Incidents
The biggest advantage for rural riders is the generally lower risk environment. Less traffic means fewer opportunities for collisions with other vehicles. Theft rates are typically lower, especially for motorcycles that might be stored in private garages or on properties away from main roads.
Imagine riding through the quiet scenic routes of Vermont or the expansive plains of Texas. While you still need to be vigilant, the constant threat of a multi-car pileup or a sudden lane change from an inattentive driver is significantly reduced. This translates to fewer claims for insurers, which in turn allows them to offer lower premiums for liability and comprehensive coverage. For many riders, the peace of mind that comes with these lower rates is a significant perk of country living. If you're looking for How to Get Cheap Motorcycle Insurance, a rural address can be a major factor in your favor.
Animal Hazards and Longer Emergency Response Times
However, rural riding isn't entirely without its specific risks. One of the most common dangers on country roads is wildlife. Deer, elk, coyotes, and other animals frequently cross roads, especially at dawn and dusk. Hitting an animal on a motorcycle can be incredibly dangerous and cause extensive damage to your bike. While comprehensive coverage typically covers animal strikes, the frequency of these incidents in rural areas can still be a factor in pricing.
Another consideration for rural riders is potentially longer emergency response times. If you have an accident far from a major town, it might take paramedics, police, or roadside assistance longer to reach you. While this doesn't directly impact your premium in the same way as accident frequency, it's a risk factor that insurers are aware of, and it's a critical personal safety consideration for riders. This is where options like Roadside Assistance Towing for Motorcycles become even more valuable.
Comparing Costs: A Look at the Numbers
Let's put some hypothetical numbers to this urban vs. rural discussion. While exact rates vary wildly based on your specific bike, riding history, age, coverage choices, and even your credit score, we can illustrate the general difference.
Consider a 35-year-old rider with a clean record, riding a 2023 Honda Rebel 500 with full coverage (liability 50/100/25, plus comprehensive and collision with a $500 deductible).
Table: Illustrative Annual Motorcycle Insurance Costs
| Location Type | Example City/State | Est. Annual Premium Range | Key Risk Factors Influencing Cost |
|---|---|---|---|
| Major Urban | Los Angeles, CA | $1,200 – $2,500+ | High traffic, theft, cost of repairs |
| Miami, FL | $1,000 – $2,000+ | High traffic, uninsured motorists | |
| New York City, NY | $1,500 – $3,000+ | Extreme density, high theft, high labor | |
| Dallas, TX | $900 – $1,800+ | High traffic, rapidly growing population | |
| Suburban | Austin, TX (outskirts) | $700 – $1,400 | Moderate traffic, moderate theft |
| Orlando, FL (surrounding) | $600 – $1,200 | Moderate traffic, some tourist density | |
| Rural | Small town, Wyoming | $400 – $900 | Low traffic, low theft, animal strikes |
| Countryside, Iowa | $350 – $800 | Very low traffic, animal strikes |
Note: These ranges are purely illustrative and can vary significantly based on individual circumstances, chosen coverage, and insurance provider.
As you can see, the difference can be substantial. A rider in a bustling metropolis like New York City might pay three to four times what a rider in rural Wyoming pays for essentially the same coverage on the same bike. This table really drives home why understanding What Affects Your Motorcycle Insurance Rate? is so important.
Getting Accurate Quotes for Your Location
So, how do you find out what your specific costs will be? The best approach is always to get personalized quotes. Don't just rely on general averages. Insurance providers like The Zebra can help you compare multiple quotes side-by-side, allowing you to input your specific zip code and see how it impacts your rates. This is crucial because even within a single city, rates can vary by neighborhood due to localized crime rates or accident hotspots.
When you're comparing quotes, be transparent about your garaging address, as this is a primary factor. Don't be tempted to use a rural address if you primarily live and park your motorcycle in the city – this is considered insurance fraud and can lead to policy cancellation or denial of claims.
Strategies to Potentially Lower Your Premiums
Regardless of whether you live in a city or the countryside, there are always steps you can take to try and reduce your motorcycle insurance costs.
Taking Advantage of Discounts
Insurance companies offer a plethora of discounts that many riders overlook. Completing a motorcycle safety course, for instance, can often net you a significant discount, and it's invaluable training no matter where you ride. Many insurers, including major players like Progressive and Geico, offer these.
Bundling your motorcycle insurance with your car insurance or home insurance policy is another common way to save a good chunk of change. Having a clean driving record, owning a multi-bike policy, or even having anti-theft devices installed on your motorcycle can all contribute to lower premiums. Always ask your potential insurer about all available discounts when you're looking for How to Compare Motorcycle Insurance Quotes.
Choosing the Right Coverage Wisely
While it might be tempting to opt for the absolute minimum coverage to save money, it's essential to understand the implications. Your state will have Motorcycle Insurance Requirements by State, but minimum liability often isn't enough to protect your assets if you're involved in a serious accident.
However, you can still be smart about your coverage. Consider your bike's age and value. For an older, less valuable motorcycle, carrying comprehensive and collision might not be worth the cost if the annual premium eats up a significant portion of its market value. For newer, financed bikes, full coverage is usually required, and Do You Need Gap Insurance on a Motorcycle? might be a smart addition. Evaluate your deductibles – a higher deductible means lower premiums, but also a larger out-of-pocket expense if you file a claim.
Improving Your Riding Skills and Record
The longer you ride without accidents or traffic violations, the better your insurance record becomes, and the lower your rates will generally be. Insurance companies reward safe, experienced riders. If you're a new rider, your rates will likely be higher, but they tend to decrease significantly around the age of 25 and with several years of riding experience.
Even if you've had a minor fender bender, focus on safe riding going forward. Over time, that incident will have less impact on your premiums. Remember, a clean record is one of the most powerful tools you have in your arsenal for keeping insurance costs down, whether you're navigating urban traffic or cruising rural roads.
Final Thoughts on Location and Premiums
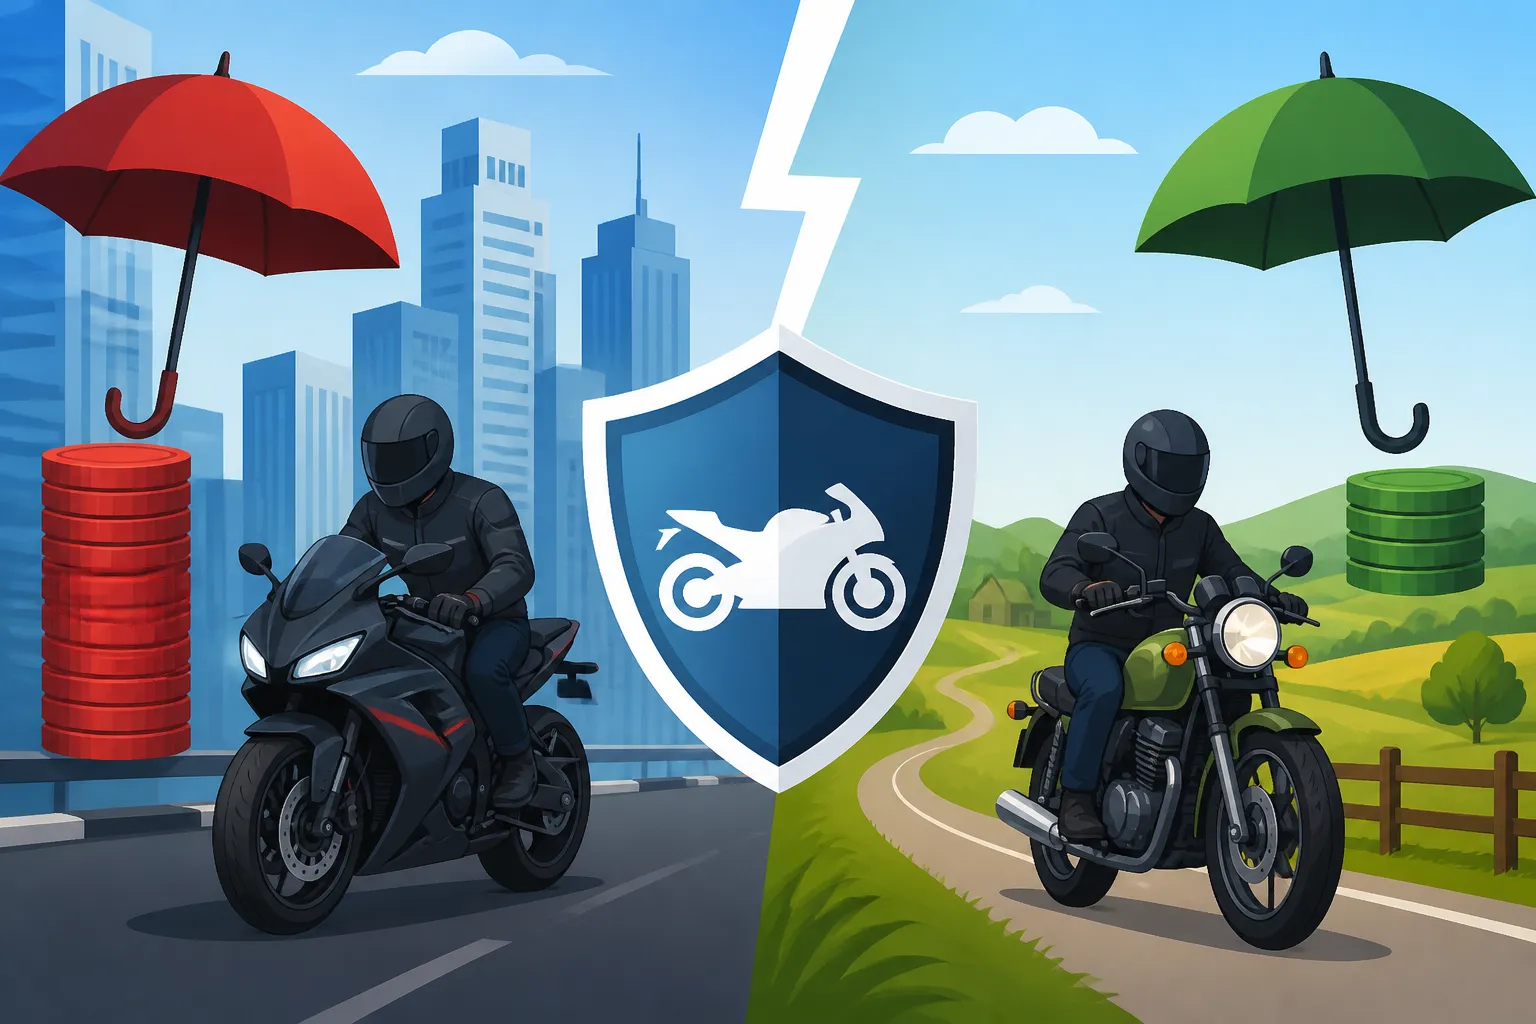
Ultimately, where you live is a non-negotiable factor in your motorcycle insurance rates. Big cities generally come with higher premiums due to increased traffic density, higher accident rates, greater theft risks, and elevated costs for repairs and medical services. Rural areas, while presenting lower overall risk, do have their own unique considerations like wildlife hazards.
The key takeaway is to be informed. Don't assume anything about your rates based on a friend's experience in a different area. Get personalized quotes from several providers like The Zebra, compare them carefully, and explore all the discounts you might qualify for. By understanding the interplay between your location and other rating factors, you can make smarter choices about your coverage and ensure you're getting the best possible value for your motorcycle insurance.
Disclaimer
Please remember that this article provides general information and guidance. Motorcycle insurance laws, requirements, and rates vary by state, insurer, and individual circumstances. It is crucial to consult with a qualified insurance professional and review specific policy documents to understand your coverage and obligations.