Motorcycle Insurance Cost by Age
Many new riders walk into a dealership, fall in love with a bike, and sign the papers only to be hit with a massive wave of sticker shock when they call for an insurance quote. Whether you are eighteen and facing a premium that costs more than your bike or sixty-five and wondering why your rates are suddenly creeping up, this guide breaks down exactly how age dictates your costs and how you can fight back against rising premiums.
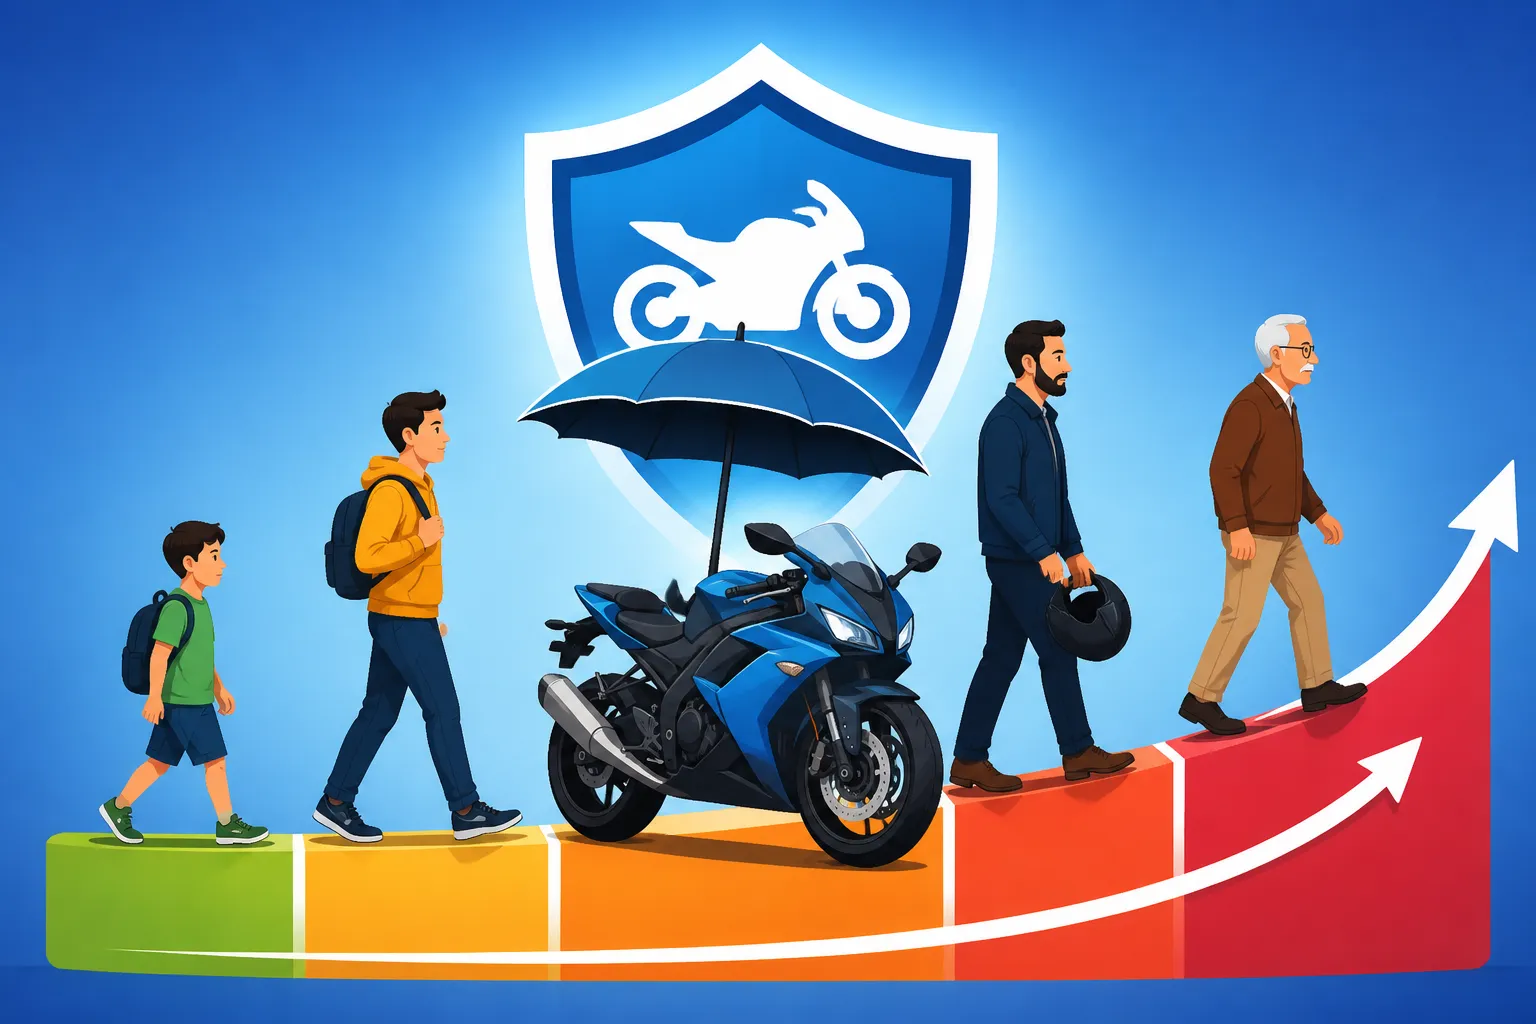
Why Age is the Biggest Factor in Your Premiums
It might feel unfair to be judged solely by the date on your birth certificate, but from an insurance company's perspective, age is one of the most reliable predictors of risk. When actuaries sit down to crunch the numbers, they aren't looking at your individual character; they are looking at decades of data that show a direct correlation between age and the frequency of accidents. It’s a frustrating reality of the industry, but understanding the "why" can help you navigate the system more effectively.
The Statistics of Risk and Probability
Insurers rely on the Law of Large Numbers. This mathematical principle suggests that while they can't predict what you specifically will do on a Tuesday afternoon, they can predict with startling accuracy what ten thousand 19-year-olds will do. Statistically, younger riders are more likely to engage in high-risk behaviors, such as speeding or lane splitting in heavy traffic, which leads to more frequent and more expensive claims.
When you look at the Average Motorcycle Insurance Cost by State and compare it against age brackets, the disparity is glaring. For a teenager, the statistical likelihood of a total loss claim is significantly higher than for a rider in their 40s. This is why a younger rider often pays triple what an older rider pays for the exact same motorcycle. It isn't personal; it's a reflection of the millions of miles of data points that show youth and high-speed machinery can be a volatile combination.
Experience vs Biological Age
There is often a debate among riders about whether "age" or "years of riding experience" matters more. The truth is that they are both heavy hitters, but they represent different types of risk. A 40-year-old brand-new rider is still a risk because they lack the "muscle memory" of a veteran, but they are often viewed more favorably than a 19-year-old brand-new rider. Why? Because the 40-year-old's prefrontal cortex—the part of the brain responsible for impulse control—is fully developed.
Insurers know that an older rider is more likely to check their blind spots, wear all the gear, and avoid riding in torrential downpours. Even if that older rider is just starting out, their overall life experience usually translates to more conservative decision-making on the road. This is why How Much Is Motorcycle Insurance for a Beginner? can vary so wildly depending on whether that beginner is a college student or a mid-career professional.
How Maturity Impacts Decision Making on the Road
Maturity isn't just a buzzword; it’s a financial metric in the insurance world. Younger riders often view motorcycles as a source of adrenaline and social status. This can lead to riding in groups where "one-upmanship" occurs, leading to speeds that the rider isn't equipped to handle. On the flip side, older riders often view their bikes as a therapeutic escape or a tool for long-distance touring.
Insurance companies track these behavioral trends through claim types. Younger riders are frequently involved in single-vehicle accidents involving excessive speed or "laying the bike down" in a corner. Older riders, while still involved in accidents, are more likely to be involved in low-speed mishaps or accidents where a third party was at fault. Because the rider's behavior is the only thing the insurer can't control, they use age as a proxy for that missing information.
Breaking Down Costs for Teens and Young Adults
If you are under 25, I’m not going to sugarcoat it: you are in the "danger zone" for insurance pricing. This is the period of your life where you will likely pay the highest premiums you will ever see. It can be incredibly disheartening to realize that your annual insurance bill might be $2,000 or $3,000 for a bike that only cost you $5,000. However, understanding the specific milestones within this age group can help you plan for the future.
The 18 Year Old Sticker Shock
Eighteen is a milestone for many things, but in the world of motorcycling, it’s often the year of the most expensive quotes. At this age, you have virtually zero driving history and zero riding history. You are a blank slate of high risk. If you are looking into How Much Is Motorcycle Insurance for an 18 Year Old?, you should prepare for quotes that look like a mortgage payment.
At eighteen, many riders gravitate toward sport bikes like the Yamaha R6 or Kawasaki Ninja series. This is a "double whammy" for your wallet. You are a high-risk rider on a high-risk machine. To get these rates down, many riders find that they need to stay on their parents' policy or look for specific high-risk carriers. Even using a tool like The Zebra to compare multiple quotes can reveal massive price swings, as some companies simply don't want the risk of a teen on a sport bike and will "price themselves out" of your consideration.
The Magic Number 25
For decades, the age of 25 has been the "promised land" for vehicle insurance. While the drop isn't as instantaneous as a birthday cake appearing on your desk, it is a very real statistical cliff. Once you hit 25, insurers generally stop viewing you as a "youthful operator" and start moving you into the standard risk pool. This is often the point where you see your premiums drop by 20% to 35% overnight, provided you have maintained a clean record.
During this transition, it is vital to re-shop your policy. The company that was the "least expensive" when you were 21 might not be the most competitive now that you are 25. You should look at How Much Does Motorcycle Insurance Go Down at 25? to understand the potential savings. This is also a great time to consider increasing your coverage limits. Since the base price is lower, you can often afford much better protection—like higher liability limits or uninsured motorist coverage—for the same total price you were paying a few years prior.
Strategies to Lower High Youth Rates
Just because you are young doesn't mean you are powerless. There are several proactive steps you can take to mitigate the age penalty. First and foremost, take a certified safety course. Completing an MSF (Motorcycle Safety Foundation) course not only gives you the skills to stay alive but also provides a guaranteed discount with almost every major insurer.
Another strategy is to choose your bike wisely. Instead of a 600cc supersport, consider a 300cc or 400cc "beginner" bike. The insurance on a KTM 390 Duke is going to be a fraction of the cost of a Suzuki GSX-R 600. Additionally, consider your location. If you are a student, where you park the bike matters. A bike kept in a locked garage in a low-crime zip code will always be cheaper to insure than one chained to a light pole in a busy city. If you're struggling to find a quote you can afford, checking a platform like The Zebra can help you find specialized carriers that might be more lenient toward younger riders.
The Sweet Spot: Premiums for Riders in Their 30s and 40s
By the time you hit your 30s, you have likely entered what many in the industry call the "Goldilocks" phase of insurance. You are young enough to have quick reflexes and good health, but old enough to have a proven track record of stability. For many riders, this is the decade where they finally stop worrying about the cost of insurance and start focusing more on the quality of their coverage.
Stabilization of Rates
In your 30s and 40s, the wild fluctuations of your 20s are usually a thing of the past. As long as you don't have a string of speeding tickets or a DUI, your rates will likely remain flat or even decrease slightly each year. This is the period where insurance companies start to compete for your business through "loyalty" and "vanishing deductible" programs.
At this stage, you are also more likely to be an experienced rider. If you have been riding since your early 20s, you now have 10+ years of experience, which is a massive plus in the eyes of an underwriter. If you are curious about how these rates look on a national level, checking the Average Motorcycle Insurance Cost by State can give you a baseline. Most riders in this bracket find that they can get excellent full coverage for a few hundred dollars a year, rather than a few thousand.
Impact of Life Changes: Marriage and Homeownership
It might seem strange that getting married or buying a house affects your motorcycle insurance, but these are "stability markers." Insurers have found that people who own homes and are married are statistically less likely to take unnecessary risks on the road. They have "skin in the game"—assets to protect and a family to come home to.
When you bundle your motorcycle insurance with your homeowners or renters insurance, the discounts can be substantial. This is also the phase where you might start looking at Multi-Bike Discount: Insuring More Than One Motorcycle. Many riders in their 30s find they want a "fleet"—perhaps a cruiser for the weekends and a smaller bike for commuting. Bundling these together on a single policy is one of the most effective ways to drive down the per-bike cost.
Balancing Performance and Price
This is often the age where "disposable income" starts to increase, and riders might look at more powerful or expensive machines. Whether it's a high-end Ducati or a fully-loaded BMW GS, the value of the bike becomes a bigger factor in the premium than the age of the rider. Even if you are 40 and have a perfect record, insuring a $25,000 motorcycle will never be "cheap."
However, because your age-related risk is so low, you can often afford to add specialized coverages that younger riders might skip. Things like Accessories & Custom Parts Coverage Explained become very important if you’ve added thousands of dollars in aftermarket exhausts, luggage, or chrome. In this "sweet spot," your insurance strategy shifts from "how do I afford to ride?" to "how do I best protect my investment?"
Mature Riders: Insurance Trends for 50s and 60s
Once you cross into your 50s, you are entering the era of the "Silver Rider." This is a massive demographic for the motorcycle industry, and insurance companies love this group. Riders in their 50s and early 60s often have the highest levels of experience and the most stable financial profiles. However, this is also a time when the type of bike you ride begins to heavily influence your rates.
The Experience Discount
For a rider in their 50s who has been on two wheels for thirty years, the "experience discount" is at its peak. You have likely seen every road condition and survived every close call. Insurers recognize this as a mastery of the craft. If you haven't filed a claim in five or ten years, you are essentially a "preferred" client.
This is the time to look for "Accident Forgiveness" clauses in your policy. Some insurers will guarantee that your first minor mishap won't raise your rates if you’ve been with them for a certain period. If you are shopping around for a new policy at this age, using a comparison site like The Zebra can help you find companies that specifically target "mature" riders with niche discounts that aren't advertised to the general public.
Transitioning to Touring and Cruisers
Statistically, riders in their 50s and 60s tend to move away from sport bikes and toward touring bikes, trikes, or heavy cruisers. This shift is great for your insurance premiums. A Harley-Davidson Insurance Cost analysis usually shows that these bikes, while expensive to buy, are much cheaper to insure relative to their value than high-performance bikes.
These bikes are built for comfort and distance, not for triple-digit speeds on the highway. Because the "intended use" of the bike is more conservative, the premium reflects that lower risk. If you are making the switch from a sportier bike to something like a Gold Wing or a Road Glide, you will likely see a significant drop in your liability and collision costs, even if the new bike is worth more than the one you traded in.
When Rates Might Start Climbing Again
There is a subtle turning point that often happens in the late 60s. While you still have all that experience, insurers begin to factor in the physical realities of aging. Slower reaction times and potential medical issues can start to nudge premiums back up. It’s not a drastic spike like the one teens face, but it is a noticeable trend.
During this time, it's wise to stay proactive. Keep your record clean and consider taking a "refresher" safety course. Many states and insurance companies offer specific discounts for seniors who complete a safety evaluation. This proves to the insurer that despite your age, your skills are still sharp. You should also check Motorcycle Insurance Cost for Riders Over 50 to see how your current rates stack up against the national average for your age bracket.
Senior Riders and the Golden Years of Riding
Riding into your 70s and beyond is a badge of honor in the motorcycling community. However, the insurance landscape for senior riders is unique. At this stage, the focus shifts heavily toward medical coverage and liability protection, as the physical consequences of an accident are much more severe for an older body than for a younger one.
Managing Physical Reflexes and Insurance Risks
As we age, our peripheral vision, night vision, and reaction times naturally decline. Insurance companies are acutely aware of these biological changes. While they won't cancel your policy just because you turned 75, they do monitor claim trends for this age group. In some cases, insurers may require more frequent policy reviews or medical disclosures if you are involved in an accident.
To keep your rates low as a senior, you might consider "usage-based" insurance. If you only ride 1,000 miles a year on sunny Sunday mornings, tell your insurer. Many companies offer low-mileage discounts that can significantly offset any age-related increases. Being honest about how and when you ride can save you a lot of money in the long run.
Medical Coverage and Liability Concerns
One of the biggest frustrations for senior riders is the cost of Medical Payments (MedPay) for Riders. Because injuries take longer to heal and medical complications are more likely in older adults, the "Personal Injury" portion of your insurance can become more expensive. If you have excellent health insurance or Medicare, you might be tempted to skip this, but always check how your primary health insurance handles "motor vehicle accidents" first.
Liability coverage is also crucial at this stage. If you are a senior with significant assets (like a paid-off home or retirement savings), you need high liability limits. If you are found at fault in an accident, your age won't protect your assets from a lawsuit. Ensure your limits are high enough to protect what you've worked your whole life to build.
The Importance of Safety Courses for Seniors
I cannot stress this enough: safety courses are your best friend as an older rider. Not only do they provide a discount, but they also give you a controlled environment to test your reflexes. Many seniors find that moving to a "trike" or a three-wheeler is a great way to stay on the road while reducing the physical strain of balancing a heavy bike.
If you make the switch to a three-wheeler, be sure to look into Best Motorcycle Insurance for a Trike. These vehicles often have different insurance structures than two-wheeled bikes. They are generally seen as more stable and safer, which can lead to surprisingly affordable premiums for riders in their 70s and 80s.
National Average Comparison Table
To give you a better idea of what to expect, here is a breakdown of estimated annual premiums by age for a standard cruiser or commuter bike with "Full Coverage" (Collision, Comprehensive, and Liability). These are national averages and will vary based on your specific location and bike type.
| Age Bracket | Estimated Annual Premium | Risk Category | Key Factor |
|---|---|---|---|
| 16 – 19 | $1,800 – $3,500+ | High | Lack of experience / Brain development |
| 20 – 24 | $1,200 – $2,200 | Moderate-High | Higher speed-related claims |
| 25 – 34 | $600 – $900 | Standard | The "Magic 25" drop / Life stability |
| 35 – 49 | $400 – $700 | Low | Peak stability and experience |
| 50 – 64 | $350 – $600 | Very Low | Transition to touring/cruisers |
| 65 – 75 | $450 – $800 | Moderate | Biological reaction time factors |
| 76+ | $600 – $1,000+ | Increasing | Physical vulnerability / Medical costs |
How to Get the Best Rates Regardless of Your Age
No matter which age bracket you fall into, you shouldn't just accept the first quote you get. The insurance market is incredibly competitive, and different companies have different "appetites" for risk. One company might hate insuring 20-year-olds but love insuring 50-year-olds, while another company might be the exact opposite.
Shopping Around with Aggregators
The single most effective way to save money is to compare multiple quotes. In the past, this meant calling six different agents and repeating your life story six times. Today, you can use a service like The Zebra to compare dozens of companies at once. This gives you a clear "bird's eye view" of the market.
You might find that a smaller, specialized company like Dairyland or Markel offers a much better rate for your specific age and bike than a "big name" carrier. Don't be afraid to switch companies every few years. Loyalty is great, but in the insurance world, the "new customer" discount is often much larger than the "loyal customer" discount.
Maintaining a Clean Record
This is the "not-so-secret" secret to cheap insurance. A single speeding ticket can increase your rates by 10% to 20% for three years. A DUI can double or triple your rates and might even make you uninsurable with standard carriers, forcing you to look for SR-22 for Motorcycles: When It's Required.
If you do get a ticket, see if your state allows you to take a "Safety School" or "Diversion Program" to keep the points off your license. Keeping your "MVR" (Motor Vehicle Record) clean is the best way to ensure that your age works for you, not against you.
Bundling and Multi-Policy Discounts
Finally, always ask about bundling. If you have a car, a home, or even a life insurance policy, moving them all to one carrier can save you a massive amount of money. Insurers love "sticky" customers who have multiple lines of business with them. They view these customers as more stable and less likely to switch, which they reward with significant discounts.
Even if you don't own a home, bundling your motorcycle with a renters insurance policy is usually cheaper than buying them separately. Always ask your agent to "run the numbers" both ways—separate and bundled—to see which actually saves you the most in the long run. If you're looking for the absolute lowest price, check out the Cheapest Motorcycle Insurance Companies to see which brands consistently lead the pack for your age group.
Disclaimer
This guide is for informational purposes only and does not constitute financial, legal, or professional insurance advice. Insurance rates, laws, and coverage options vary significantly by state, provider, and individual circumstances. Always consult with a licensed insurance agent or professional to discuss your specific needs and ensure you are in compliance with local regulations.